What Is a Mortgage Loan Processor? A Complete Beginner's Roadmap
ACAffinity Career Academy · October 14, 2026 · 4 min read
If someone asked you to name the most important person in a home purchase, you'd probably say the real estate agent or the loan officer. Understandable — those are the faces everyone sees. But behind the scenes, it's the mortgage loan processor who actually moves the file forward. Without a processor, that loan sits still.
So what does a processor actually do, and how do you become one? Let me walk you through it.
What a Mortgage Loan Processor Does
A mortgage loan processor is the person responsible for taking a loan application from submission to the underwriter's desk — fully packaged, verified, and compliant. Think of it as building a case. The loan officer opens the conversation with the borrower; the processor gathers and organizes every piece of evidence the underwriter needs to approve it.
On any given day, that means:
- Reviewing the loan application (the 1003) for completeness and accuracy
- Ordering and tracking third-party documents — the appraisal, title report, flood certification, and homeowner's insurance
- Collecting borrower documentation — pay stubs, W-2s, tax returns, bank statements, and anything else the loan program requires
- Verifying income, employment, and assets against program guidelines
- Running the file through automated underwriting systems (AUS) like Fannie Mae's Desktop Underwriter or Freddie Mac's Loan Product Advisor
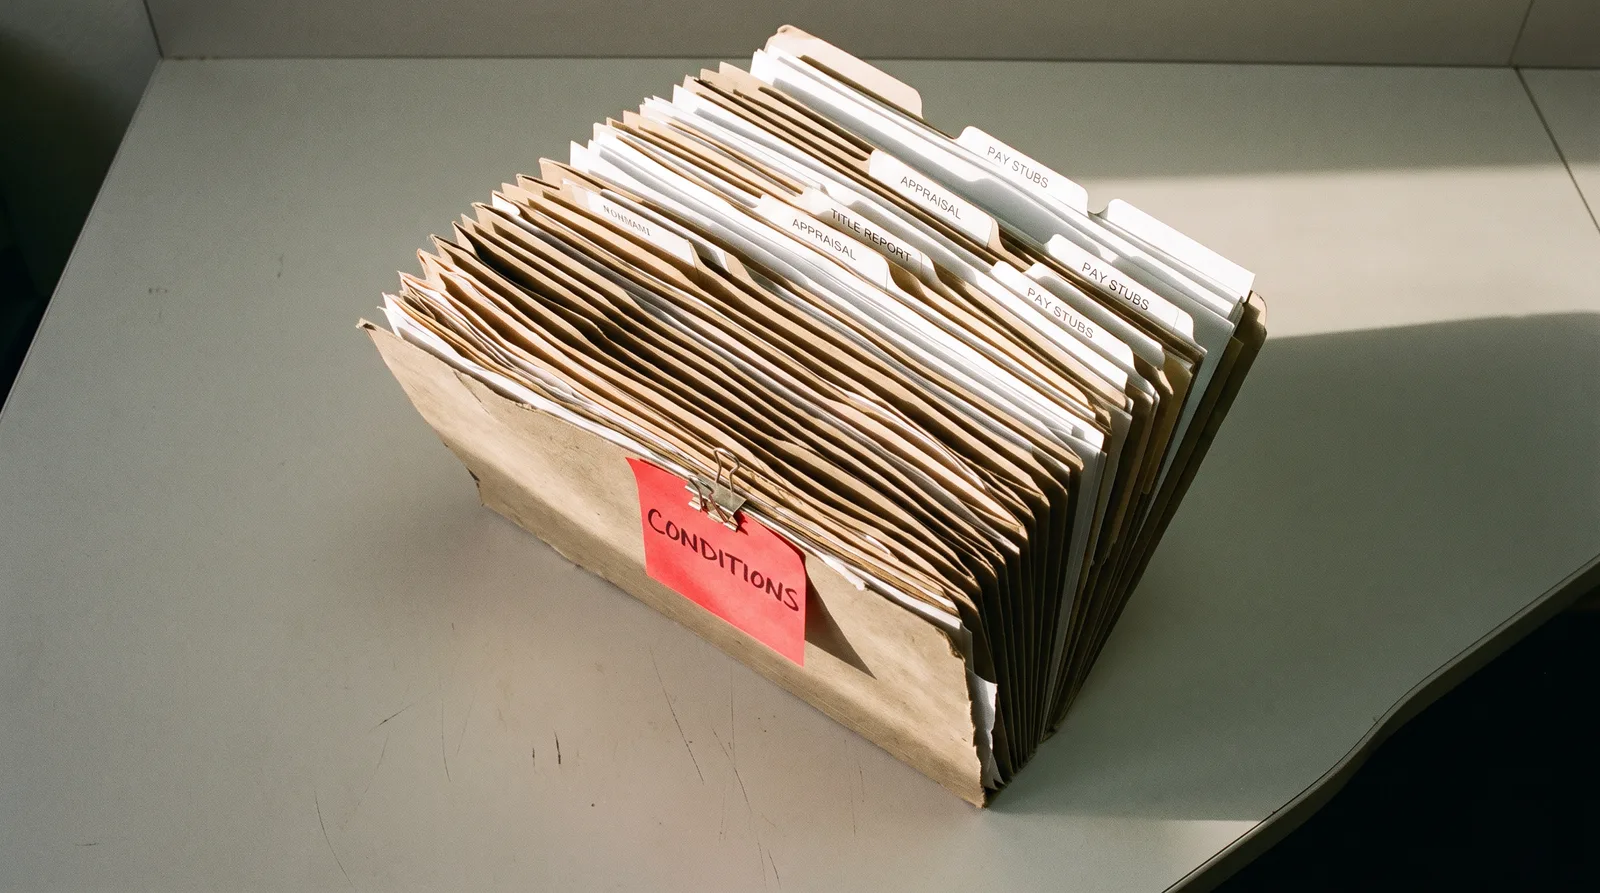
- Clearing conditions — when the underwriter comes back with a list of items needed before approval, the processor is the one who hunts them down
- Keeping everyone on schedule so the closing date doesn't slip
You are the hub. The loan officer, the borrower, the underwriter, the title company, the real estate agents — they all run through you.
The Skills That Actually Matter
You don't need a finance degree to become a processor, but you do need a specific combination of skills that not everyone naturally has.
Attention to detail is non-negotiable. A missing page from a bank statement or a name that doesn't match a government ID can derail a closing. You need to be the kind of person who notices those things before anyone else does.
Organized, deadline-driven thinking keeps you sane. Processing desks move fast, and you'll typically be working multiple files simultaneously. If you can't prioritize and track, things fall through the cracks — and in this business, cracks cost people their closing dates.
Comfort with guidelines and regulations matters more than people expect. You don't need to be a compliance attorney, but you do need to understand the basics of the Truth in Lending Act (TILA), the Real Estate Settlement Procedures Act (RESPA), and how loan program guidelines from FHA, VA, USDA, and conventional products shape what you can and can't do with a file.
Clear communication is what holds the process together. You're translating between the borrower (who is probably stressed and confused) and the underwriter (who speaks in conditions and guidelines). Being able to explain what's needed, why it's needed, and when it's due — without creating panic — is a real skill.
What the Path to Your First Role Actually Looks Like
Here's the honest roadmap, step by step.
Step 1: Learn the loan lifecycle. Before you can process a file, you need to understand every stage of one. This means getting fluent in what happens from application through closing — what documents are involved, what each party does, and what compliance checkpoints exist along the way.
Step 2: Get familiar with the paperwork. The Uniform Residential Loan Application (Form 1003), the Loan Estimate, the Closing Disclosure — these are your primary documents. You should be able to read them, understand every field, and spot what's missing or inconsistent.
Step 3: Study loan program basics. FHA, VA, USDA, and conventional (Fannie/Freddie) loans all have different requirements around credit, income, and assets. You don't need to memorize every guideline upfront, but knowing the broad strokes of each program type makes you immediately more useful on day one.
Step 4: Build your compliance foundation. Know what RESPA and TILA require in terms of disclosures and timelines. Understand what a Good Faith Estimate became (the Loan Estimate), and why the three-day rule for the Closing Disclosure exists. These aren't just rules to memorize — they protect borrowers, and understanding the why makes them stick.
Step 5: Target the right first jobs. Entry-level processors often start as loan processor assistants, mortgage operations assistants, or pipeline coordinators at mortgage companies, banks, or credit unions. These roles let you work under experienced processors while you build your file-handling instincts. Look for companies that offer mentorship or in-house training — your first processing environment will shape your habits for years.
You Don't Need to Figure This Out Alone
The mortgage industry has a reputation for being hard to break into without knowing someone on the inside. That's partly true — which is exactly why structured training matters. When you arrive at your first processing desk already knowing the lifecycle, the documents, and the compliance basics, you're not starting from zero. You're starting with credibility.
That's what I built Affinity Mortgage Processing School to do: give you the foundation that turns a new role from overwhelming into manageable. If this roadmap resonates with you, come see what the school covers — I'd love to help you get there.
Want to go deeper than a blog post?
Affinity Mortgage Processing School
Master every stage of the mortgage loan lifecycle — from application intake to clear-to-close — with practical, compliance-ready training built for real processing desks. Whether you're breaking into the industry or sharpening your skills, this school turns complexity into confident, job-ready competence.
Start learning — $297/yr