Conventional vs. FHA Loans: What Every New Mortgage Processor Needs to Know
ACAffinity Career Academy · October 26, 2026 · 4 min read
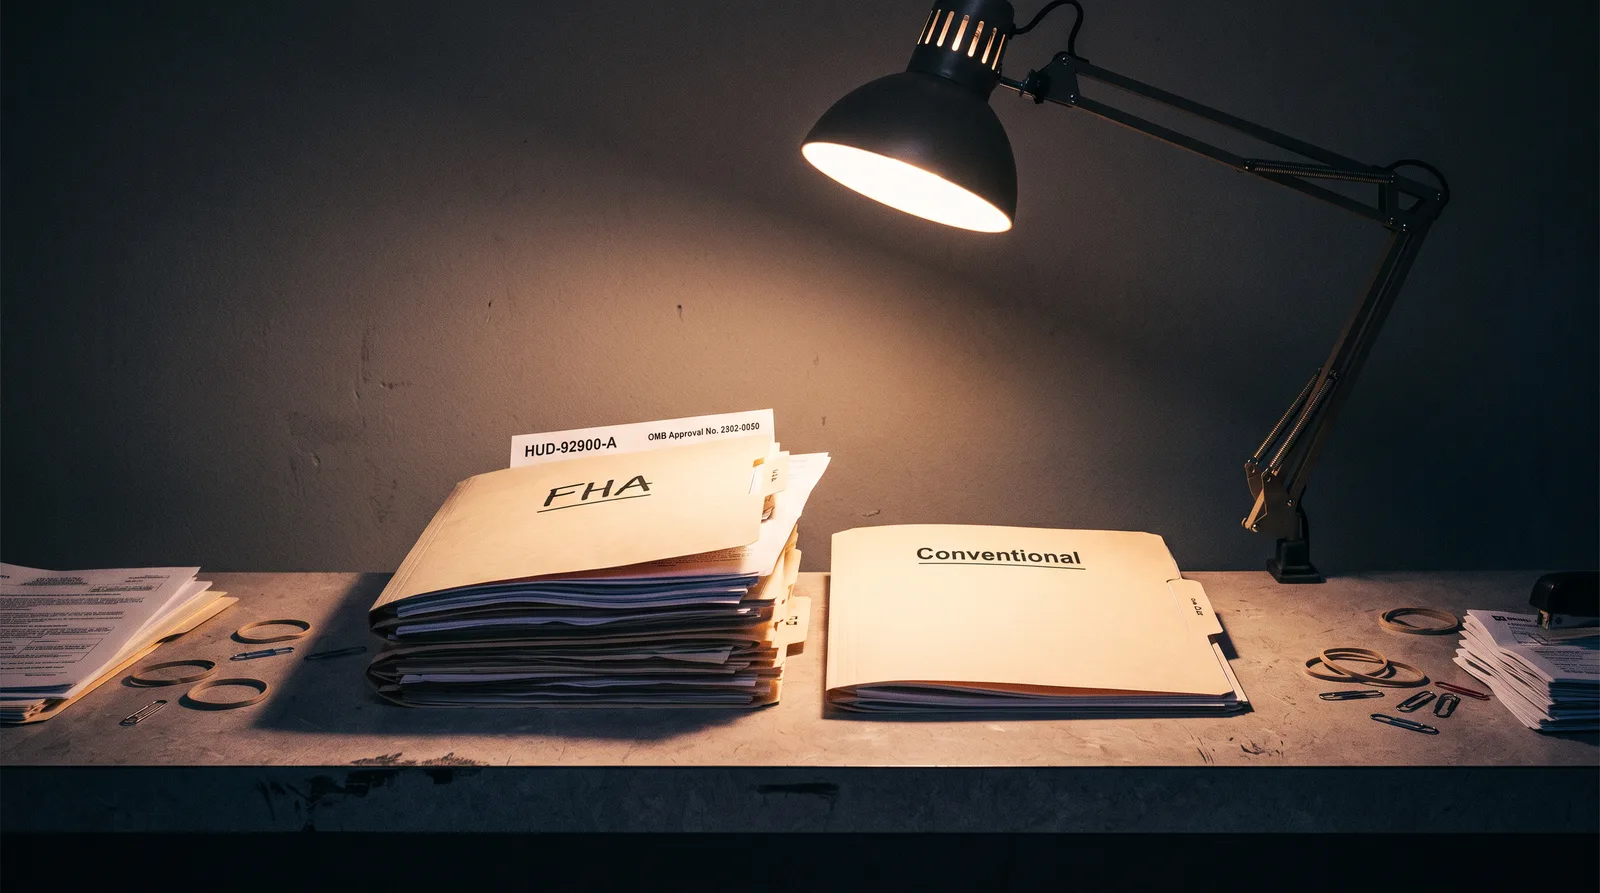
When you're new to the processing desk, one of the first things that will trip you up is assuming a loan file is a loan file. It isn't. The moment you see "FHA" versus "Conventional" at the top of that 1003, the rules of the game shift. Documentation requirements change. Overlays change. What the underwriter will flag changes. Get familiar with these differences early, and you'll move files faster, with fewer conditions, and a lot less back-and-forth.
The Foundation: Who's Backing the Loan?
This is the core distinction, and everything else flows from it.
A conventional loan is not government-backed. It's typically sold to Fannie Mae or Freddie Mac on the secondary market, which means it follows their guidelines — known as the Selling Guide for Fannie and the Single-Family Seller/Servicer Guide for Freddie. Your lender may also layer on their own overlays on top of those.
An FHA loan is insured by the Federal Housing Administration, a division of HUD. That insurance is what protects the lender if the borrower defaults — and it's exactly why FHA guidelines exist in a separate universe from conventional. You'll live by HUD Handbook 4000.1 on every FHA file.
Knowing which rulebook governs the file in front of you isn't a technicality. It tells you which checklists to pull, which forms to include, and which conditions are non-negotiable.
Credit and Qualifying: What the Numbers Mean on Each Side
On a conventional loan, the minimum credit score for most conforming products is 620, though many lenders set their overlay higher. Debt-to-income (DTI) ratios are generally capped around 45–50%, depending on compensating factors and automated underwriting approval.
On an FHA loan, borrowers can qualify with a score as low as 580 for the standard 3.5% down payment option — or even down to 500 with 10% down, though many lenders won't go that low due to overlays. FHA is often more flexible on DTI as well, sometimes allowing up to 57% with a strong automated approval.
As a processor, this means your FHA files will often carry borrowers with thinner credit profiles. That's not a problem — it's just a signal to look more closely at the credit explanation letters, late payment patterns, and any collections or judgments that need to be addressed before submission.
The Documentation Differences That Matter Most
Both loan types require your standard income, asset, and employment docs — W-2s, pay stubs, tax returns, bank statements. But FHA adds layers.
FHA-specific documents you'll handle:
- Case Number Assignment — Every FHA loan gets a case number from FHA Connection before you can order the appraisal. This is step one, full stop.
- HUD-92900-A (Addendum to the URLA) — Required on every FHA file. Don't let it fall through the cracks.
- FHA Amendatory Clause — Must be signed before the purchase agreement is ratified. If it's missing or signed out of order, you have a problem.
- CAIVRS Authorization — You must clear the borrower through HUD's Credit Alert Verification Reporting System to confirm they don't have a federal delinquency or prior FHA claim. No clearance, no close.
- MIP Disclosure — Borrowers must be informed of the Mortgage Insurance Premium structure. Make sure it's in the file and signed.
Conventional files skip all of that. But they come with their own nuances — particularly around private mortgage insurance (PMI) when the loan-to-value is above 80%. You'll need the PMI approval from the MI company in the file before closing, and that approval has its own conditions to track.
The Appraisal: Two Very Different Standards
This is where processors get caught off guard more than anywhere else.
A conventional appraisal follows Fannie/Freddie guidelines and focuses primarily on value. Safety conditions may be noted, but they don't automatically kill the deal.
An FHA appraisal is both a valuation and a property condition inspection. The FHA appraiser is required to flag health and safety issues — peeling paint (especially in homes built before 1978), missing handrails, broken windows, exposed wiring, roof issues. If the appraiser calls for repairs, those repairs must be completed and signed off before closing. No exceptions.
As a processor, the moment you see an FHA appraisal come back with required repairs, start coordinating immediately. Get the repair list to the agent and seller, track the completion, order the re-inspection, and make sure the updated report gets to the underwriter. This sequence takes time, and it can stall your closing date if you don't stay ahead of it.
What This Means at Your Desk
The practical takeaway is this: build two separate mental checklists — one for FHA, one for conventional — and run the right one every single time. FHA files need more touchpoints, more forms, and more sequencing discipline. Conventional files have fewer moving parts but demand close attention to MI approvals, reserve requirements, and agency-specific guidelines.
Neither loan type is harder. They're just different. And knowing exactly what each one requires, before the file lands in front of you, is what separates a processor who clears conditions quickly from one who's always putting out fires.
That difference is where your value lives.
Inside Affinity Mortgage Processing School, we walk through FHA and conventional processing step by step — forms, checklists, underwriting conditions, and everything in between. If you're ready to build a real processing skillset, come learn with us.
Want to go deeper than a blog post?
Affinity Mortgage Processing School
Master every stage of the mortgage loan lifecycle — from application intake to clear-to-close — with practical, compliance-ready training built for real processing desks. Whether you're breaking into the industry or sharpening your skills, this school turns complexity into confident, job-ready competence.
Start learning — $297/yr